Make More Possible With Your Home's Equity ······
Borrow what you need, when you need it, with a revolving line of credit secured by your home.
Your Equity. Your Possibilities.
Up to
$750,000
Up to 80% CLTV
1
Home Improvements
Renovations, repairs, and upgrades.
Life's Big Moments
Celebrations, milestones, and major purchases.
Financial Flexibility
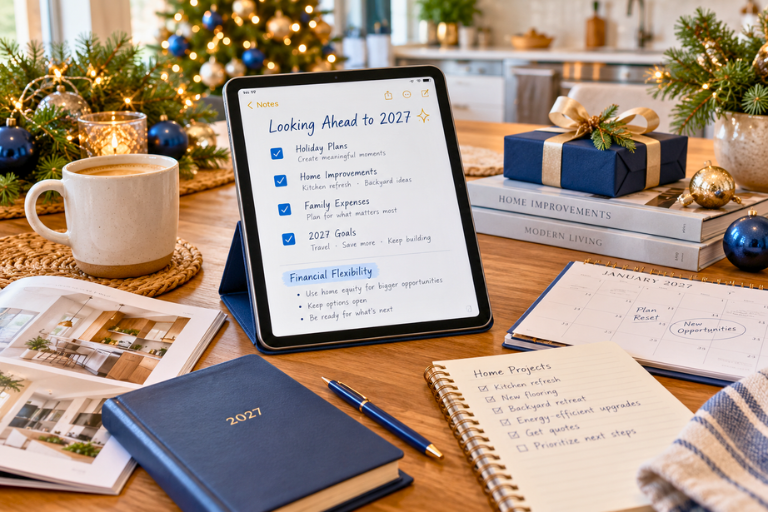
Consolidate higher-interest debt or access extra cash.
+ Enjoy 10 Years of Flexible Access to Your Funds1
······
Frequently Asked Questions
What documents do I need to apply for a HELOC?
To get started, you'll need your mortgage statement and proof of homeowners insurance.Proof of income is also required and will be requested by your HELOC representative when they contact you. Additional documents may be requested on a case-by-case basis.
What is Prime Rate and Margin when it pertains to my Member Rate?
A HELOC (Home Equity Line of Credit) prime rate is the interest rate that serves as a benchmark for setting HELOC interest rates. The prime rate is often tied to the federal funds rate set by the Federal Reserve, meaning it can fluctuate based on economic conditions and Federal Reserve policy changes.For a HELOC, the interest rate is typically expressed as the prime rate plus a margin. For example, if the prime rate is 8.75% and the margin is 0.25%, the HELOC rate would be 9.00%. This margin can vary based on the borrower's creditworthiness and the lending institution's policies.
Who is eligible for a HELOC?
Homeowners with equity in their homes. Take your home's value, and then subtract all amounts that are owed on that property. The difference is the amount of equity you have. For example, if you have a property worth $400,000, and the total mortgage balances owed on the property are $200,000, then you have a total of $200,000 in equity.2Are there fees I can expect with this process?
Estimated costs related to the process: If required, Full Appraisal Fee ($140.00-$950.00), Current Owner Search Report ($84.00), Origination Fee ($60.00), Flood Ceritication Fee ($11.00), Estimated Recording Fees ($150.00), Mobile Notary Fee ($165.00). Enjoy no application fee, annual service fee, or pre-payment fee!
Serving Southern California homeowners since 1957.
Local decisions. Personalized service.
Disclosures
1
Annual Percentage Rate. Rate shown is effective 11/01/2026 and may change without notice. Rate shown is the lowest possible and is based on FICO/Credit Score and other factors. The rate of 5.25% APR is an introductory rate valid for the first 12 months from when the Home Equity Line of Credit (HELOC) funds; after which the rate will default to the non-promotional rate which the member qualifies for based on the Prime Rate and margin disclosed at the time of funding, which is determined by creditworthiness, FICO/Credit Score and other factors. The floor rate for this promotion is 5.00% APR. This is subject to standard Downey Federal Credit Union (DFCU) credit approval. To qualify for the introductory rate member must advance a minimum of $10,000 at the time of funding the HELOC. If there is no initial advance at the time of funding, the loan will not be eligible for the discounted rate. This offer is valid from 11/01/2026 to 12/31/2026. No HELOC or other loans currently financed at DFCU are eligible. DFCU does business in accordance with the Federal Fair Housing Law and Equal Credit Opportunity Act and deposits are Federally Insured by NCUA. Membership must be in good standing in order to be approved for this loan promotion; non-members would have to establish membership before loan funding. Additional restrictions apply. Please contact a DFCU Loan Representative for complete promotional details and qualifying criteria. Other rates and terms are available.